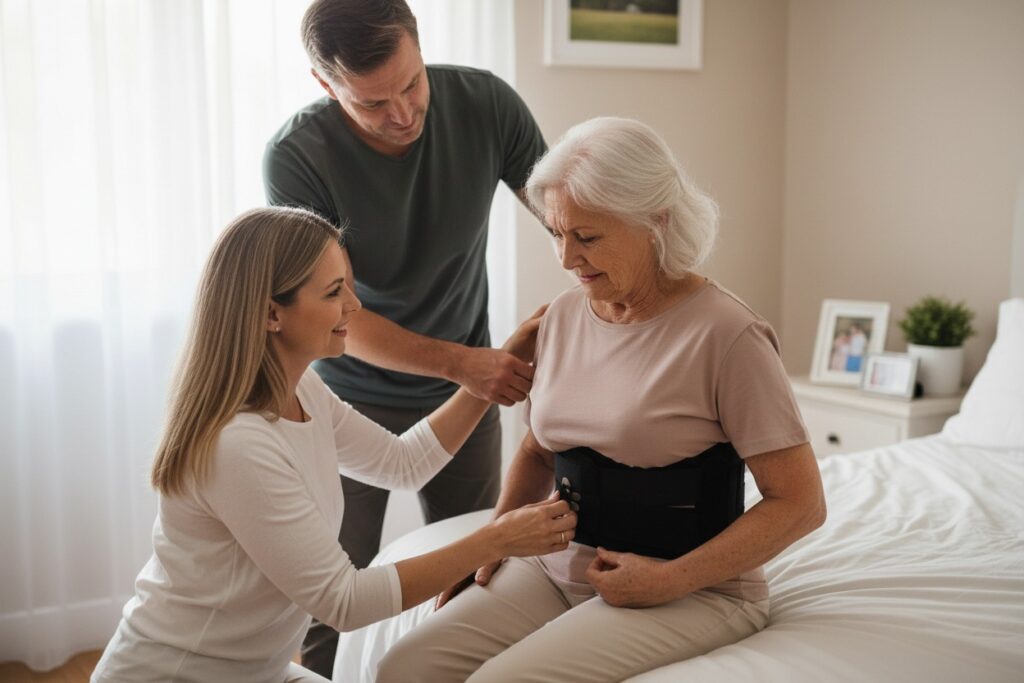
Falls in aging parents can be frightening, especially when a single fall seems to signal that something has changed.
This morning, during what should have been a routine salon visit, I found myself in an unexpectedly meaningful conversation. The lovely young lady had recently lost her grandmother to vascular dementia. Her family had known about the diagnosis for years, but when her grandmother had a fall and rapidly declined, they found themselves completely unprepared.
No time to grieve properly. No idea of the costs involved in a funeral. No insurance in place. Just shock and the overwhelming logistics that come with it.
What struck me most was what she said next, “I don’t want to do this to my family when I’m older. What can I do now to prepare?” I thought, how sweet, she’s in her twenties and she’s already thinking about protecting the people she loves.
This article is for her and for every family who is quietly wondering the same thing but doesn’t know where to start.
How Families Can Help Prevent Falls
While not every fall can be prevented, families can take simple steps to reduce risk. Start by looking around the home for common hazards: loose rugs, cluttered walkways, poor lighting, slippery bathroom floors and stairs without secure handrails. Encourage your parent to wear supportive, well-fitting shoes rather than walking in loose slippers or socks and make sure frequently used items are within easy reach so they aren’t climbing or stretching unnecessarily. A night light or tracking light is particularly useful when an aging parent needs to get up at night and maybe unsure or forgetful of their surroundings.
It’s also worth talking with their doctors about medications, vision and hearing, balance, and muscle strength. Some medications can cause dizziness or drowsiness, while changes in vision, weakness or balance problems cam make falls more likely. Regular gentle exercise that works on strength, balance and mobility can also help older adults stay steadier and more independent. The goal isn’t to eliminate every risk, it’s to make the everyday environment safer and recognize changes early before a preventable fall happens.
Why Vascular Dementia Can Catch Families Off Guard
Vascular dementia is the second most common form of dementia in the United States, affecting an estimated 1 in 10 dementia patients. It often develops after a stroke or a series of mini-strokes that restrict blood flow to the brain. Unlike Alzheimer’s, which tends to decline gradually, vascular dementia can progress in a step-like pattern with periods of relative stability followed by sudden drops, often triggered by a health event like a fall or infection.
This unpredictability is exactly why families get caught off guard. “She was doing okay” becomes “she fell and was never the same again” almost overnight. The window to plan legally, financially, emotionally can close faster than anyone expects.
Learn more: Vascular Dementia – Alzheimer’s Association
Step 1: Have the Conversation Now While You Still Can
The single most valuable thing any family can do is talk openly while their loved one still has the mental capacity to express their wishes. This includes:
- Where they want to live if they can no longer manage alone (at home with help, assisted living, or a nursing facility)
- Their wishes around medical treatment and end-of-life care
- Who they trust to make decisions on their behalf
- What kind of funeral or memorial service they would want, and whether they prefer burial or cremation
- Where important documents are kept such as wills, insurance policies, bank accounts, Social Security cards
These conversations are uncomfortable. But they are far less painful than trying to make decisions in a crisis without any guidance from the person who matters most.
Helpful conversation guide: National Institute on Aging – Family Caregiving
Step 2: Get the Legal Documents in Order
This is the area where most families are completely unprepared. If a person loses mental capacity without the right legal documents in place, family members may have no authority to manage their finances, make medical decisions, or even access their bank account without going through a lengthy and expensive court process called guardianship.
Durable Power of Attorney (POA)
A Durable Power of Attorney designates a trusted person (called an “agent”) to manage financial and legal matters if your loved one becomes incapacitated. “Durable” means it stays in effect even after the person loses mental capacity. There are two types to be aware of:
- Financial POA — covers bank accounts, paying bills, managing property and investments
- Healthcare POA (also called a Healthcare Proxy) — covers medical decisions, care arrangements, and end-of-life choices
Learn more: AARP – Power of Attorney Guide
Advance Healthcare Directive / Living Will
A living will (also called an advance directive) lets your loved one document their wishes around life-sustaining treatment, resuscitation, and end-of-life care so those decisions don’t fall on you in an already devastating moment.
Free state-specific forms: CaringInfo – Advance Directives by State
Writing or Updating a Will
A will ensures assets go to the right people and reduces family conflict at an already difficult time. If your loved one doesn’t have one — or hasn’t updated it in years — now is the time. An estate planning attorney can help, or affordable online options exist for simpler estates.
Find an estate attorney: American Bar Association – Find Legal Help
Step 3: Understand the Real Cost of Care (and Plan for It)
One of the biggest shocks families face is the true cost of elder care. According to Genworth’s annual Cost of Care Survey, the median annual cost of a private room in a nursing home in the US is over $108,000, and memory care facilities average $6,000–$8,000 per month. Home health aide services average around $27 per hour. And funerals? The median cost of a funeral with burial in the US is now over $9,000.
Key things to investigate and plan for:
- Medicare vs. Medicaid: Medicare generally does NOT cover long-term nursing home care. Medicaid does, but only once a person’s assets fall below your state’s threshold. This often requires careful planning years in advance
- Long-term care insurance: if your loved one is still in relatively good health, this may be worth exploring
- Veterans benefits: if your loved one served in the military, they may qualify for VA Aid & Attendance benefits to help pay for care
- Social Security and pension income that can contribute to care costs
- Whether a home sale or reverse mortgage is part of the financial picture
Care cost calculator: Genworth Cost of Care Survey
Medicare & Medicaid guidance: Medicare.gov – How Medicare Covers Nursing Home Care
Veterans benefits: VA.gov – Aid & Attendance Benefits
For the Young Woman Who Asked: “What Can I Do Now?”
The fact that you’re thinking about this in your twenties puts you ahead of most people. Here’s honest, practical advice for planning early in the US:
Life Insurance
Taking out life insurance when you’re young and healthy is one of the smartest financial moves you can make because premiums are significantly lower. A term life policy can cover funeral costs, outstanding debts, and provide financial security for those who depend on you. For young, healthy people, a 20- or 30-year term policy is often the most cost-effective option.
Compare policies: Policygenius – Life Insurance Comparison
Pre-Paid Funeral Plans
A pre-need funeral plan lets you lock in today’s prices and set out your exact wishes, removing the emotional and financial burden from your family entirely. Look for providers that are members of the National Funeral Directors Association (NFDA) and make sure funds are held in a state-regulated trust.
Find an NFDA member funeral home: NFDA – Find a Funeral Home
Write a Will (Even in Your Twenties)
A basic will ensures your assets go where you want them to and names who you trust to manage your affairs. For younger adults with straightforward finances, affordable online services like Trust & Will or LegalZoom can walk you through the process for well under $200. You can always update it as your life changes.
Affordable online wills: Trust & Will – Online Estate Planning
Consider a Long-Term Care Insurance Policy
Long-term care insurance helps cover the cost of nursing homes, assisted living, or in-home care if you need it later in life. Buying it young means significantly lower premiums. It’s worth getting a quote in your thirties or forties at the latest, as policies become more expensive — or unavailable — if you wait until health issues arise.
Learn more: ACL.gov – What Is Long-Term Care Insurance?
Talk to Your Own Parents Now
Use what you’ve experienced as an opening. Ask gently: Do you have a will? Is there a power of attorney in place? Is there anything you’d want me to know if something happened to you? These conversations get easier with practice, and they are one of the greatest gifts you can give each other.
When the Time Comes: What to Expect from Funeral Costs in the US
If you’re facing this now or want to understand what’s involved, here’s an honest overview of typical funeral costs across the United States:
- Basic funeral director services fee: $2,000–$3,500
- Casket: $2,000–$10,000+ (one of the largest costs, you have the legal right to purchase one elsewhere)
- Burial plot and grave opening: $1,000–$4,000+ (varies widely by location and cemetery)
- Cremation (direct): $700–$2,500
- Death certificates (you’ll need multiple copies): $10–$25 each depending on your state
- Flowers, obituary, reception: $500–$2,500+
If cost is a concern, the FTC’s Funeral Rule gives you the legal right to receive an itemized price list from any funeral home and to choose only the services you want. You are never required to buy a package.
Know your rights: FTC – The Funeral Rule
Social Security lump-sum death benefit: SSA.gov – Survivors Benefits
The Bottom Line
Preparing for the inevitable is not morbid. It is one of the most loving things you can do for the people who matter to you. Whether you’re in your twenties wondering how to protect your future family, or you’re watching a parent age and wondering what comes next — the time to plan is always now, before a crisis makes every decision harder.
Start with one conversation. Then one document. Then one call to an elder law attorney or your loved one’s doctor. Small steps taken calmly today save enormous heartache tomorrow.
If you found this article helpful, share it with someone who needs to read it. And if you have questions or want to share your own experience, leave a comment below.
Leave a Reply